Table of Contents
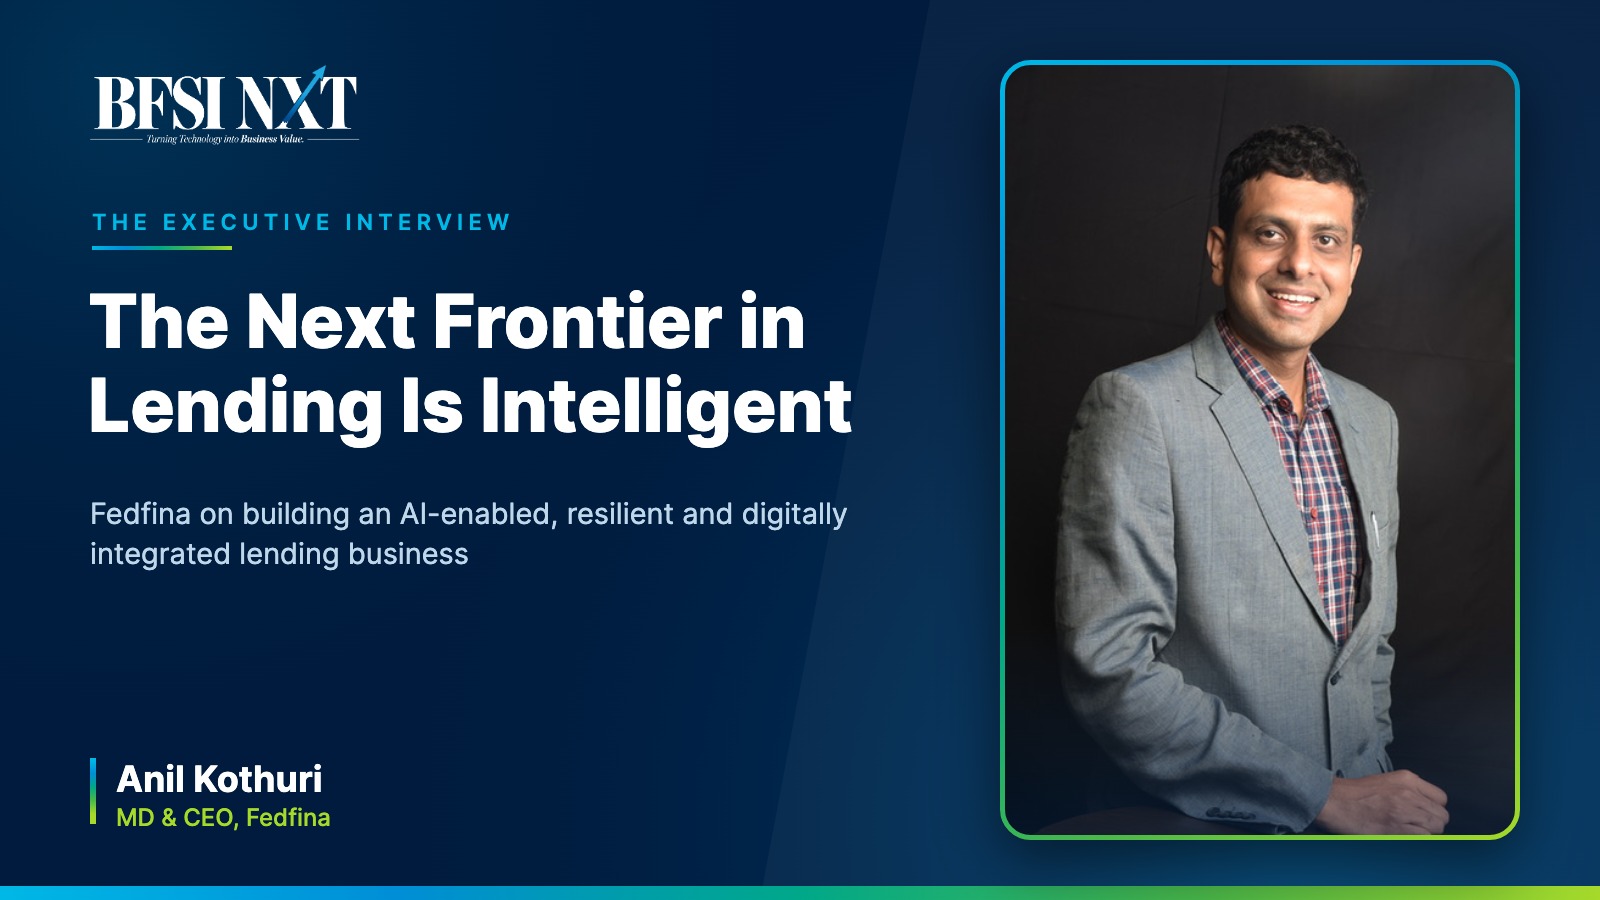
The Executive Interview
Fedfina on building an AI-enabled, resilient and digitally integrated lending business
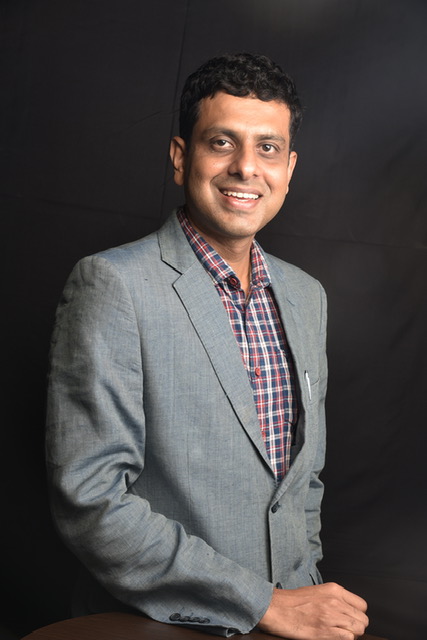
For non-bank lenders, digital transformation is moving beyond the digitisation of customer journeys. The next test is whether organisations can turn data into decisions, apply artificial intelligence responsibly and scale operations without weakening security or customer trust. Anil Kothuri, MD & CEO of Fedfina, outlines how the company is approaching that shift.
The technology agenda for financial services has become more demanding. Growth brings pressure on operating models, fragmented data can slow decision-making, and digital channels expose lenders to increasingly sophisticated fraud and cyber risks. At the same time, customers expect faster, more consistent interactions across channels.
Fedfina’s response, as described in this interview, is centred on building internal digital capabilities while selectively working with specialist technology partners. Its priorities include AI-led automation, intelligent customer engagement, data-driven lending processes and a stronger framework for security and resilience.
In this conversation with BFSI NXT, the company discusses the operational challenges shaping its technology agenda, the role of Agentic AI, its approach to partnerships and the capabilities it believes will define the next phase of lending.
1. The operating challenge
What are the most pressing technology and operational priorities for Fedfina?
Scale is one of the defining challenges for a growing financial services business. As volumes increase, the operating model must deliver faster turnaround times and greater efficiency while maintaining service quality and cost discipline.
Data is another priority. Information held across multiple systems can make it difficult to establish a reliable, enterprise-wide view of the business. The objective is to move towards a more coherent source of truth and use that information to support faster, better-informed decisions.
At the same time, the industry is moving from conventional automation towards AI-enabled processes. That transition creates opportunities, but it also raises practical questions around accuracy, explainability, responsible use and measurable returns. We need to improve the omnichannel experience while ensuring that technology investments solve real business problems.
Fraud, identity risk and cybersecurity threats continue to evolve, requiring sustained attention. Talent is equally important: skilled technology resources are in demand, and attracting and retaining the right capabilities remains a challenge. Technology transformation, therefore, is as much an organisational priority as it is a systems agenda.
2. The transformation agenda
How is Fedfina responding to these pressures?
Our approach is digital-first and increasingly AI-led, with an emphasis on developing internal capabilities rather than relying exclusively on off-the-shelf solutions. We are building and enhancing customer-facing applications, employee platforms, digital lending journeys and business portals so that our technology environment can evolve with business requirements.
Artificial intelligence is being explored across voice interactions, operational workflows, document processing and customer services. We are also looking at Agentic AI: systems that can interpret requests, analyse information, carry out defined tasks and assist employees across business functions. The opportunity is to move beyond isolated automation towards more connected, context-aware support for day-to-day work.
Customer engagement is another area of focus. AI-enabled voice bots, chatbots and omnichannel communication can help improve responsiveness and service delivery. Alongside this, data intelligence, analytics and AI models are being used to strengthen areas such as sourcing, underwriting, risk assessment and operational productivity.
None of this works without the right people and organisational structure. We are also considering HR measures, including ESOPs, as part of the effort to retain key resources. The underlying principle is to combine internal product and engineering capabilities with emerging technologies and keep the work anchored to business outcomes.
3. Trust and resilience
How are security, continuity and customer confidence being built into the digital agenda?
Security and resilience have to be designed into digital financial services, not added as a final checkpoint. At Fedfina, we regard them as foundational to the transformation programme because customer confidence depends on the reliability and protection of the systems through which they interact with us.
Our approach includes security-by-design practices across applications, infrastructure and digital journeys, supported by regular Vulnerability Assessment and Penetration Testing, application security assessments and functional testing. These activities help identify weaknesses and strengthen the security posture of our systems.
Technology initiatives also need to operate within applicable regulatory and risk-management requirements. This includes alignment with relevant RBI guidelines, cybersecurity requirements, data protection standards and internal controls. Access management, role-based permissions, secure integrations and data governance are important parts of protecting information across digital platforms.
Operational resilience requires continued attention to application performance, database optimisation, infrastructure security, monitoring, backup and recovery mechanisms. As AI use expands, governance must extend to data access, sensitive information, prompt security, output validation, usage restrictions and human intervention.
The principle is clear: innovation cannot come at the expense of security, compliance or customer confidence. The pace of adoption must be matched by appropriate safeguards.
Anil Kothuri, MD & CEO, Fedfina
4. The innovation ecosystem
What role do technology partners and startups play in the journey?
Partnerships help us access specialist capabilities, explore emerging technologies and shorten the distance between experimentation and implementation. We see them as complements to our internal product and engineering capabilities, rather than substitutes for building a strong technology foundation of our own.
In AI and Generative AI, we are working with technology platforms and providers to explore large language models, Agentic AI, intelligent document processing and enterprise applications. Voice AI is another area of collaboration, with use cases that include lead qualification, welcome calls, customer engagement and support for personal discussions.
Within the digital lending ecosystem, fintech integrations support capabilities such as payments, e-NACH, credit assessment, KYC and other components of the lending journey.
An initiative that reflects our interest in external innovation is Startup Friday. It provides startups with an opportunity to present emerging technologies and solutions directly to our CEO, CXOs and business leaders. It also gives us a structured way to assess whether a solution addresses a relevant NBFC requirement and, where appropriate, explore a proof of concept or potential partnership.
The test for a partnership is not the novelty of the technology alone. It is whether the capability can be applied to a real business need and produce a meaningful outcome.
5. The next phase
What will shape the future of lending at Fedfina?
We see the next phase as a shift from digital enablement towards more intelligent and increasingly autonomous operations. Several capabilities are likely to shape that evolution.
Agentic AI could support stages of the lending lifecycle, from customer onboarding and document verification to underwriting and servicing. Intelligent document processing can help extract and validate information from KYC, financial and property-related documents, while supporting the identification of potential inconsistencies or fraud indicators.
Customer engagement will continue to evolve through voice AI, conversational AI and multilingual interactions. At the operational level, hyperautomation offers the prospect of connecting repetitive processes end to end, reducing manual intervention and improving turnaround times. Enterprise AI assistants can also help employees access information and make more informed decisions.
Our long-term vision is an intelligent lending ecosystem in which digital platforms, data, AI and human expertise work together. The goal is to support faster decisions, stronger risk management, a better customer experience and sustainable business growth.
Technology will be an important enabler, but the real measure of progress will be how effectively it is applied to improve the business and the experience of customers.
The BFSI NXT View
Fedfina’s priorities reflect a wider shift in the NBFC sector. The digital agenda is expanding from front-end convenience to the operating core of lending: data quality, underwriting support, fraud controls, employee productivity and resilience.
The company’s emphasis on internal capabilities, AI exploration and structured engagement with startups points to a model in which institutions combine their understanding of business requirements with specialist external innovation. The challenge will be to move promising use cases into dependable, governed operations.
As lenders assess the potential of Agentic AI and greater automation, competitive advantage is likely to depend not simply on adoption, but on disciplined execution: clear business objectives, reliable data, appropriate human oversight and security built into the design.