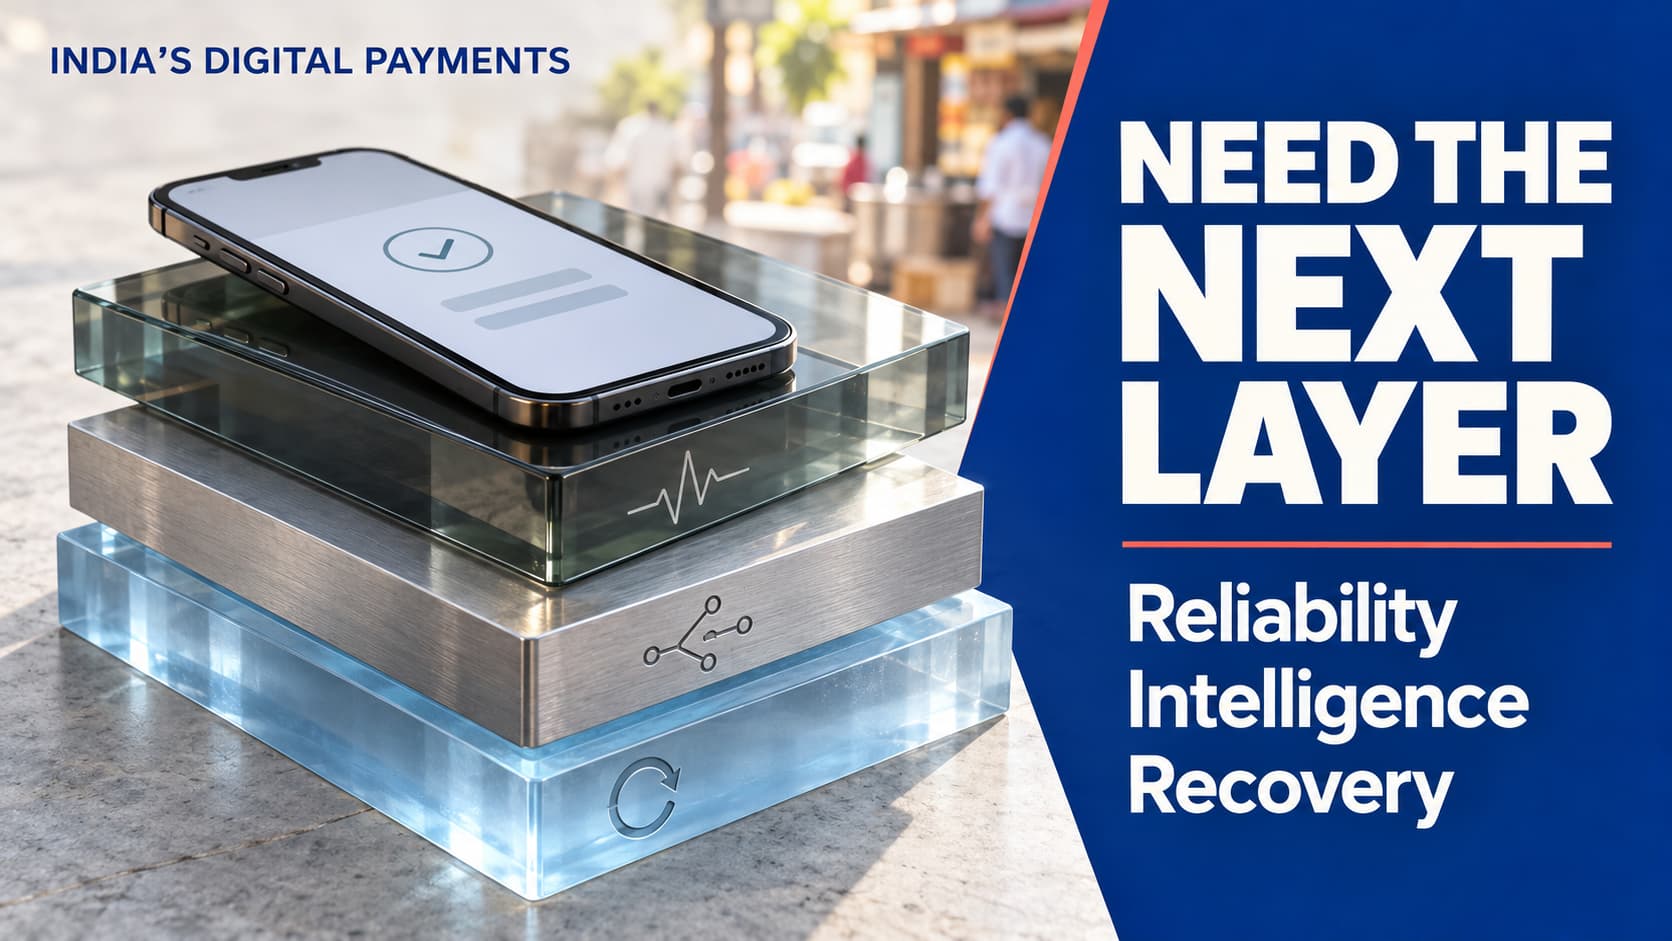
As digital payments become routine, the quality of the ecosystem will be judged by dependable transactions, fraud controls and effective dispute resolution.
Success raises expectations
When digital payments become part of everyday life, users expect transactions to be fast and dependable. Failed or delayed payments, confusing status messages and slow dispute resolution can erode confidence even when the payment interface is simple.
Design for failure as well as success
Payment providers and their partners should test how systems behave during outages, network interruptions, timeouts and duplicate requests. Clear transaction states, reconciliation controls and customer communication can reduce uncertainty when a payment does not complete as expected.
Use intelligence to spot abnormal activity
Analytics and AI can help identify suspicious patterns and improve operational monitoring. Models should be tested against changing behaviour and monitored for false positives, while high-risk decisions should have clear review and escalation paths.
Map third-party dependencies
Digital payment journeys rely on interconnected banks, processors, technology providers, networks and merchants. Providers need visibility into these dependencies, incident responsibilities and recovery arrangements—not just contractual assurances.
Treat dispute handling as product design
Customers should be able to understand what happened, what action is required and when they can expect an update. Dispute metrics and recurring failure patterns should inform product and operational improvements.
The leadership takeaway
The next phase of digital payments is not only about more transactions; it is about making each transaction dependable, explainable and recoverable.
Sources and further reading
- PwC — Indian Payments Handbook 2025–2030
- Deloitte India — State of Financial Services in India
Related reading
- DBS Bank India and Juspay Expand DBS MAX for Multi-Gateway Collections
- YES BANK and Open Announce AI-Led i-Mandate for Recurring Payments