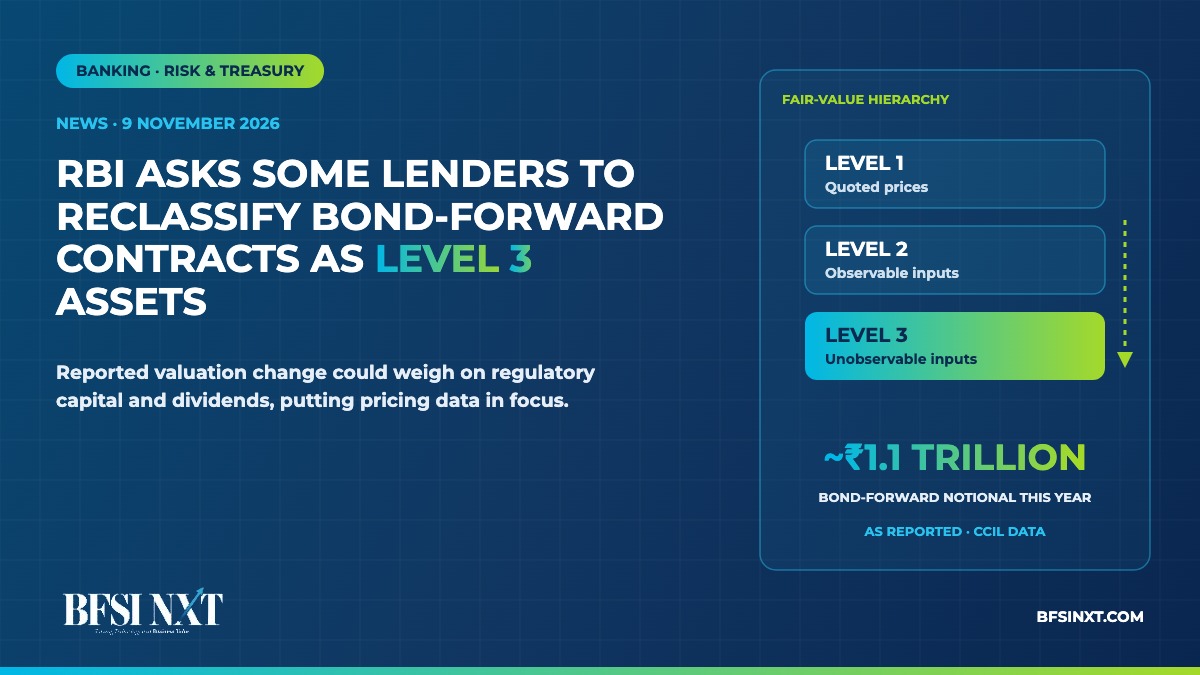
A reported change in valuation treatment could affect banks’ regulatory capital and dividend capacity, while increasing the importance of reliable pricing data and market infrastructure.
The Reserve Bank of India has told some lenders that bond-forward contracts should be valued using Level 3 inputs, according to people familiar with the matter cited by Bloomberg and reported by Business Standard.
Level 3 valuation is used when a financial instrument cannot be reliably priced using observable market information and therefore depends more heavily on an institution’s own assumptions. The classification can have implications for regulatory capital and may constrain dividend distributions under applicable rules.
Banks commonly sell bond-forward contracts to insurers, which use them to lock in future bond prices and manage interest-rate risk. The notional value of such trades was reported at around ₹1.1 trillion this year, based on clearinghouse data.
Banks have discussed the issue with the Fixed Income Money Market and Derivatives Association of India and have sought greater pricing information from the Clearing Corporation of India. CCIL has separately begun trials of an electronic bond-forward trading platform that could improve price transparency.
Why it matters for BFSI: The development matters to treasury, risk, finance and technology teams. Better market data, transparent pricing and robust valuation systems can influence capital treatment, financial reporting and risk management.
Source: Business Standard / Bloomberg, 9 November 2026